Strategic Portfolio Scaling: Moving from One Property to Multiple in NSW
A disciplined framework to scale from one investment property to a multi-asset portfolio in New South Wales. Equity release, serviceability, and risk control.
Acquiring your first residential investment property is a commendable financial milestone, but the true compounding power of real estate emerges when you successfully scale into a multi-asset portfolio. Transitioning from one property to three, four, or more requires a fundamental evolution in strategy—shifting your focus from simple property selection toward debt architecture, equity release sequencing, and proactive risk mitigation.
The Equity Release Mechanism: Unlocking Usable Equity
Most multi-property investors do not fund secondary and tertiary deposits out of everyday salary savings. Instead, they harness capital growth in their initial asset to extract usable equity via supplemental home loan splits.
Usable equity is generally defined as 80% of your current property’s verified market value minus your outstanding mortgage balance. For instance, if your initial Sydney purchase is now valued at ,400,000 with an existing loan of ,000, your 80% lending ceiling is ,120,000—releasing up to ,000 in equity to fund deposits and stamp duty on subsequent acquisitions.
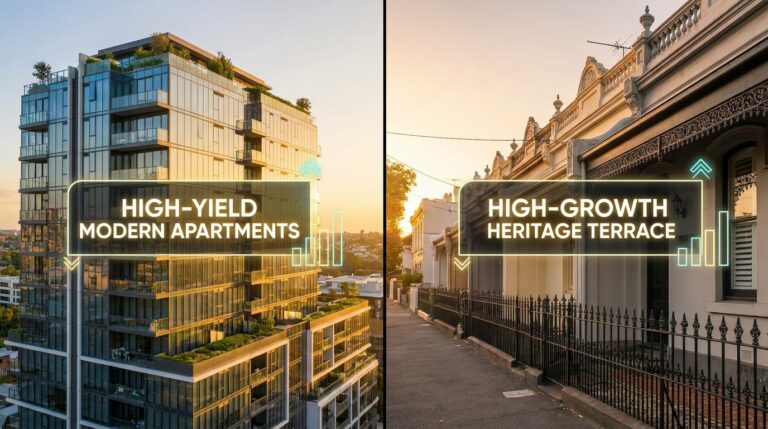
Balancing capital accumulation against ongoing portfolio outgoings as outlined in rental yield vs capital growth in Sydney property ensures each newly acquired asset contributes positively to your long-term wealth trajectory.
Scaling a portfolio requires strategic equity release, serviceability buffers, and strict asset diversification.
The Serviceability Ceiling and How to Navigate It
While equity funds deposits, borrowing serviceability dictates whether banks will approve additional mortgage loans. Every debt you take on consumes borrowing capacity, particularly under statutory stress tests detailed in our breakdown of how Australian lenders calculate true borrowing capacity.
To overcome serviceability roadblocks, experienced investors diversify lender relationships across non-bank and tier-two credit providers whose assessment metrics take a holistic view of rental incomes and negative gearing offsets, rather than keeping all borrowing concentrated within a single major bank.
The Golden Rule: Never Cross-Collateralize
One of the most dangerous structural traps when scaling is ‘cross-collateralization’—allowing a single lender to secure multiple properties under one overarching loan agreement. If one asset underperforms or is forced into sale, the bank controls the proceeds and can restrict equity access across your entire portfolio. Always insist on standalone loan facilities with independent title security.
Asset Isolation: Standalone loans ensure each property remains legally segregated, protecting other holdings if market conditions fluctuate.
Refinancing Agility: You can refinance or release equity from one property without requiring bank valuations across your entire portfolio.
Discretionary Control: When an asset is sold, surplus funds flow directly to your accounts rather than the bank dictating debt paydowns.
Entity Structuring: Advanced investors consult legal advisors regarding discretionary family trusts and corporate beneficiaries to optimize land tax thresholds in NSW.
Maintaining adequate liquidity buffers—such as six to twelve months of living and mortgage expenses held in dedicated offset facilities—is the ultimate safeguard against temporary tenant vacancy cycles, emergency maintenance repairs, and interest rate fluctuations as your portfolio expands across New South Wales.
Summary: Build with Discipline
Scaling a multi-property portfolio is an endurance journey requiring patient capital accumulation, rigorous risk management, and professional debt structuring. Explore our full suite of asset building resources in the Investment Property Strategy category.