Understanding LVR and How to Avoid Lenders Mortgage Insurance (LMI)
Learn what Loan-to-Value Ratio (LVR) means and explore proven strategies to avoid paying expensive Lenders Mortgage Insurance (LMI) on Sydney property.
In the Australian property finance landscape, two acronyms dictate the terms of almost every mortgage application: LVR (Loan-to-Value Ratio) and LMI (Lenders Mortgage Insurance). For property purchasers in high-value metropolitan markets like Sydney, understanding how these mechanisms operate can literally save tens of thousands of dollars in avoidable upfront capital charges.
What is Loan-to-Value Ratio (LVR)?
Loan-to-Value Ratio represents the percentage of a property’s assessed value that a bank or lender agrees to finance. It is calculated by dividing the total borrowing amount by the property’s purchase price (or formal valuation).
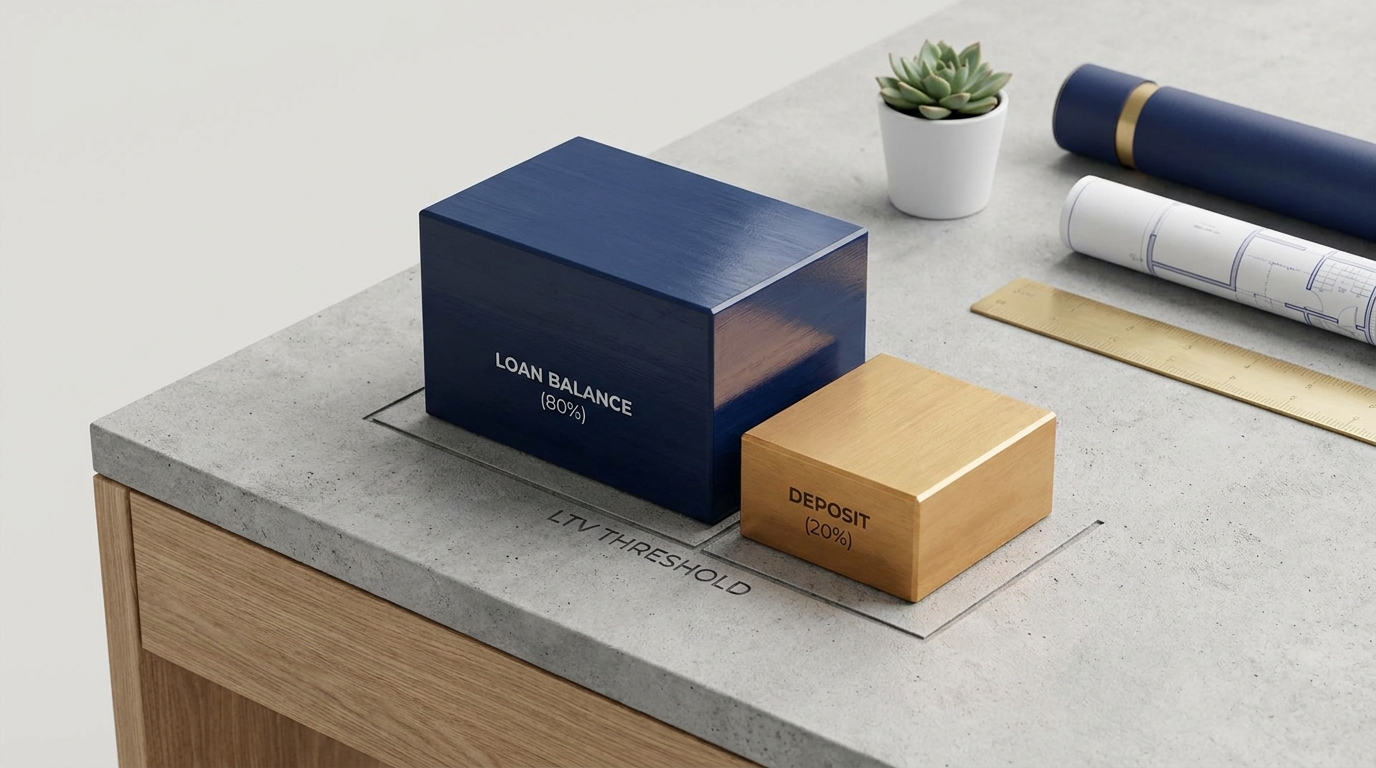
For instance, if you purchase a Sydney apartment for ,000,000 with a deposit of ,000, your loan balance is ,000, representing an LVR of exactly 80%. If your deposit is only ,000, your loan is ,000, pushing your LVR to 90%.
Crossing the 80% LVR threshold triggers Lenders Mortgage Insurance charges unless an exemption applies.
The True Nature of Lenders Mortgage Insurance (LMI)
Whenever an applicant’s LVR exceeds 80%, lenders view the loan as higher risk. To protect themselves against potential financial loss in the event of borrower default, the bank takes out an insurance policy—and charges the premium directly to the borrower as a capitalized fee or upfront cost.
Crucially, LMI protects the bank, not the borrower. If you default and your property is repossessed and sold at a loss, the insurer reimburses the bank’s shortfall and subsequently retains legal rights to recover those losses directly from you.
Proven Strategies to Avoid or Minimize LMI
Accumulate an 80% Deposit: The cleanest path to avoiding LMI is saving a genuine 20% deposit plus purchasing costs (such as transfer duty, conveyancing fees, and inspection charges).
Professional Industry Waivers: Select tier-one lenders offer LMI exemptions up to 90% or even 95% LVR for qualified professionals, including medical doctors, dentists, certified accountants, corporate lawyers, and registered veterinary surgeons.
Family Security / Guarantor Loans: A close family member (typically parents) can pledge equity in their own residential property as supplemental security, reducing the effective loan-to-value ratio below 80% without requiring additional cash savings.
Lender Risk-Fee Alternatives: Some non-bank lenders offer specialized low-deposit loans with internal risk fees that are significantly lower than standard commercial LMI premiums.
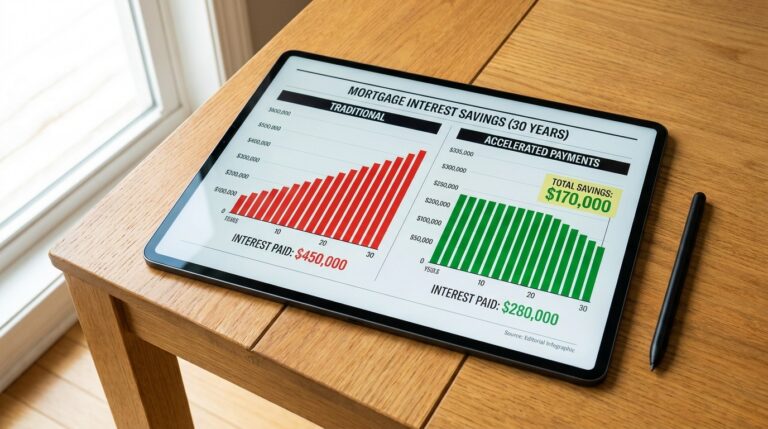
Once your loan is established, deploying our strategies in offset accounts vs redraw facilities will help you compound long-term interest reductions and build equity faster.
Government Schemes Providing LMI Relief
Eligible purchasers can also utilize Australian Government initiatives like the Home Guarantee Scheme (HGS), administered through Housing Australia. Under this initiative, the government guarantees up to 15% of the loan value, allowing first home buyers to purchase with as little as a 5% deposit without incurring LMI fees.
Strategic Conclusion: Weighing Cost vs Market Timing
LMI is not inherently bad; paying a ,000 premium may allow you to enter a rapidly appreciating market 18 months sooner than saving a full 20% deposit, during which time property values may rise by ,000. However, it should always be a deliberate financial choice. Browse our full Finance & Mortgages category for more expert lending analysis.