Offset Accounts vs Redraw Facilities: Which Saves More Interest?
Compare 100% offset accounts against redraw facilities. Learn the critical tax, liquidity, and interest-saving differences for Australian property owners.
When structuring an Australian residential mortgage, two features are frequently discussed as powerful tools for reducing interest charges over the life of a loan: 100% offset accounts and redraw facilities. While both mechanisms help borrowers lower the total interest calculated on their mortgage balance, they operate under fundamentally different banking mechanics and carry major taxation implications, particularly if your home later becomes an investment property.
How Both Features Reduce Daily Interest
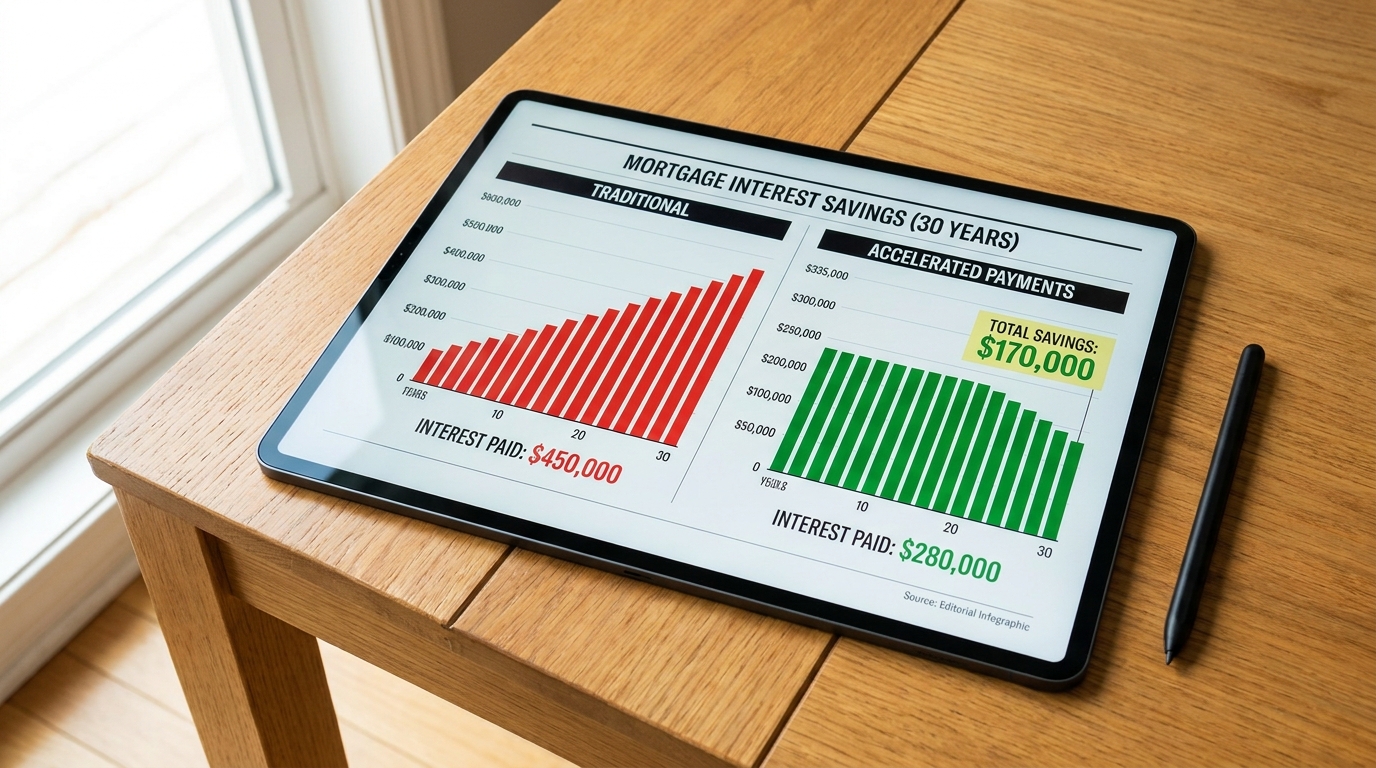
In Australia, home loan interest is calculated daily and charged monthly. Both offset accounts and redraw facilities utilize available cash to reduce the principal balance against which daily interest is calculated.
For example, on a ,000,000 mortgage with ,000 held in either an offset account or redraw facility, the lender calculates interest on only ,000. Over a 30-year amortization schedule, this simple dynamic can save tens of thousands of dollars and shave years off your loan term.
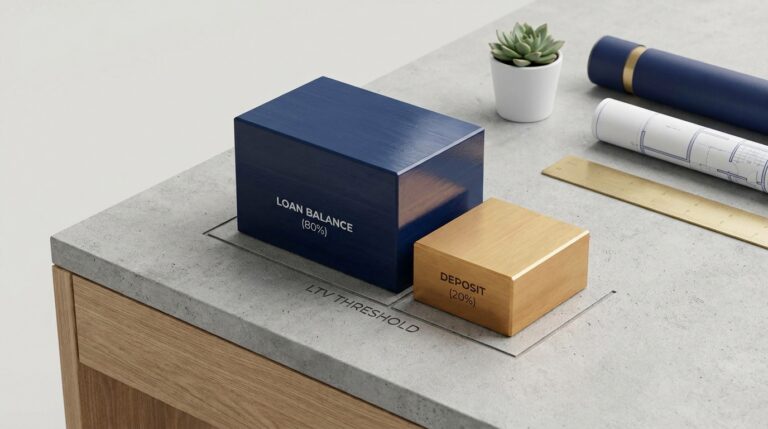
Before selecting a loan product, understanding understanding LVR and how to avoid LMI provides essential clarity on your total loan-to-value parameters.
Offset accounts provide daily interest reduction with immediate liquidity and vital tax segregation.
1. The 100% Offset Account: Ultimate Flexibility and Tax Protection
An offset account is a distinct, standard transaction account linked directly to your home loan. Cash deposited into this account remains 100% liquid; you can deposit your salary, link a debit card, and pay everyday bills via EFTPOS.
Tax Deductibility Preservation: If you later turn your owner-occupied home into an investment property, funds withdrawn from an offset account do not alter the loan’s tax status. The full loan balance remains tax deductible.
Ownership Control: The money sits in your account, not inside the bank’s loan facility.
Multiple Offset Buckets: Many modern lenders allow multiple offset sub-accounts linked to a single loan, enabling granular budgeting for taxes, renovations, and school fees.
A redraw facility is not a bank account; it is a feature within your loan allowing you to draw back extra principal payments you have made beyond your scheduled monthly repayments.
The major danger occurs if you later convert the property into a rental asset. Under Australian Taxation Office (ATO) ruling TR 2000/2, pulling funds out of a redraw facility constitutes a new borrowing. If those funds are used for non-income-producing purposes (like buying a car or a new home), the interest on that portion of the loan is strictly non-deductible.
Head-to-Head Comparison
Feature
100% Offset Account
Redraw Facility
Account Type
Separate transaction account
Feature within loan account
Accessibility
Immediate (ATM/Debit card)
Online transfer (1-2 days)
Annual Fee
Typically – package fee
Usually free or low fee
Investment Tax Protection
Excellent (maintains loan character)
High risk of contaminating tax deductions
Final Strategic Recommendation
For buyers who value immediate liquidity or plan to convert their residence into an investment asset down the track, a 100% offset account is well worth any modest annual fee. Discover more practical loan structuring insights in our Finance & Mortgages resource library.