The Pre-Approval Playbook: What Sydney Buyers Need Before Inspecting
A complete step-by-step guide to securing formal mortgage pre-approval in Sydney. Essential documentation, credit score checks, and lender turnaround times.
Attending Saturday open home inspections without formal finance pre-approval is one of the most common—and dangerous—mistakes made by prospective Sydney property buyers. In a fast-moving real estate market where competitive properties often sell within days via off-market negotiations or intense auctions, having verified conditional finance gives you the confidence to submit legally binding offers without risking your hard-earned deposit.
What Exactly is Mortgage Pre-Approval?
Mortgage pre-approval (also referred to as conditional approval or approval in principle) is a formal assessment conducted by a bank or lending institution confirming the maximum dollar amount they are prepared to lend you, subject to specific conditions such as a satisfactory property valuation.
Understanding the underlying calculations detailed in our guide on how Australian lenders calculate true borrowing capacity ensures you do not inadvertently push your target pre-approval ceiling beyond your realistic debt serviceability limits.
Pre-approval provides buying confidence and sets a clear, non-negotiable bidding ceiling.
Step 1: Assemble the Core Verification Documentation
Australian credit underwriters require comprehensive documentary evidence before issuing a genuine credit-assessed pre-approval. Submitting incomplete files leads to protracted delays and multiple credit inquiries that can depress your credit score.
Income Verification: Your two most recent computer-generated payslips, along with your latest PAYG payment summary or ATO Notice of Assessment.
Self-Employed Requirements: Two consecutive years of complete business and personal tax returns, financial statements, and ATO portal tax debt checks.
Assets and Liabilities: Six months of continuous transaction account statements showing genuine savings, plus latest statements for credit cards, personal loans, and HECS/HELP debt.
Identity Documentation: Primary photo identification complying with Australian anti-money laundering (AML) protocols.
First-time purchasers should also review our comprehensive breakdown of NSW first home buyer grants and stamp duty exemptions to ensure state concessions are accurately factored into their required cash reserves.
Step 2: Fully Assessed vs Automated System Approvals
Not all pre-approvals are created equal. An automated ‘system-generated’ pre-approval generated in seconds online has not been reviewed by a human credit assessor and carries high risk of rejection once a formal purchase contract is submitted.
Always demand a fully credit-assessed pre-approval, where a designated banking credit officer has reviewed your payslips, verified your expenses against statutory criteria, and signed off on your file.
Duration and Expiry Terms
In Australia, most mortgage pre-approvals remain valid for 90 days. If you do not exchange contracts within this window, the lender will require updated payslips and bank statements to extend the pre-approval for another 90 days, provided your financial circumstances remain unchanged.
Auction Caution: Pre-Approval is Not a Guarantee
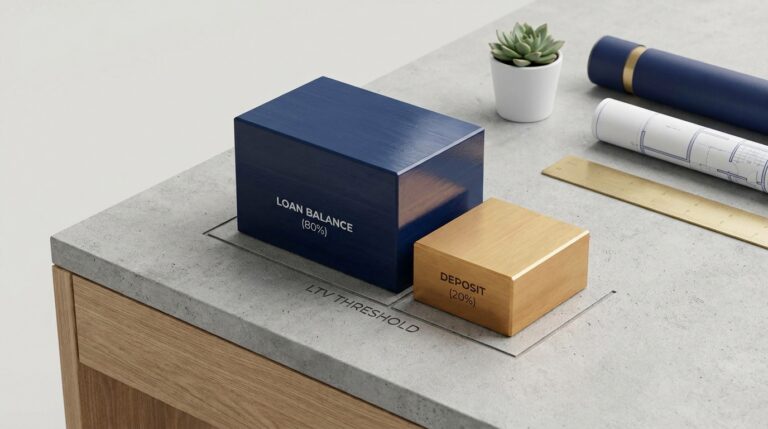
Crucially, Sydney buyers must understand that purchasing at auction requires 100% unconditional financing. Even with a formal pre-approval, the lender will still perform a desktop or physical bank valuation of the property once contracts are exchanged. If the bank’s independent valuer values the property below the purchase price, you must fund the shortfall out of your own cash reserves, making conservative bidding beneath your pre-approval ceiling vital.
Summary: Inspect with Total Confidence
Armed with a genuine, credit-assessed pre-approval, you transform from a curious observer into a qualified, decisive buyer capable of negotiating aggressively. Reach out through our Contact page to connect with our accredited advisory network before attending your next inspection.